

Why regular folks are moving to app-first credit
People want fast, no-nonsense credit that fits a busy life. That’s why many are checking options like didi prestamos straight from their phones. No long lines, less paperwork, and clearer terms beat the old bank dance for a lot of folks. Mobile onboarding, quick underwriting, and instant digital cards cut the wait time. In big cities like Mexico City, where commuters already use apps for rides and food, switching finance to the same flow just makes sense.
What DiDi Finanzas puts on the table
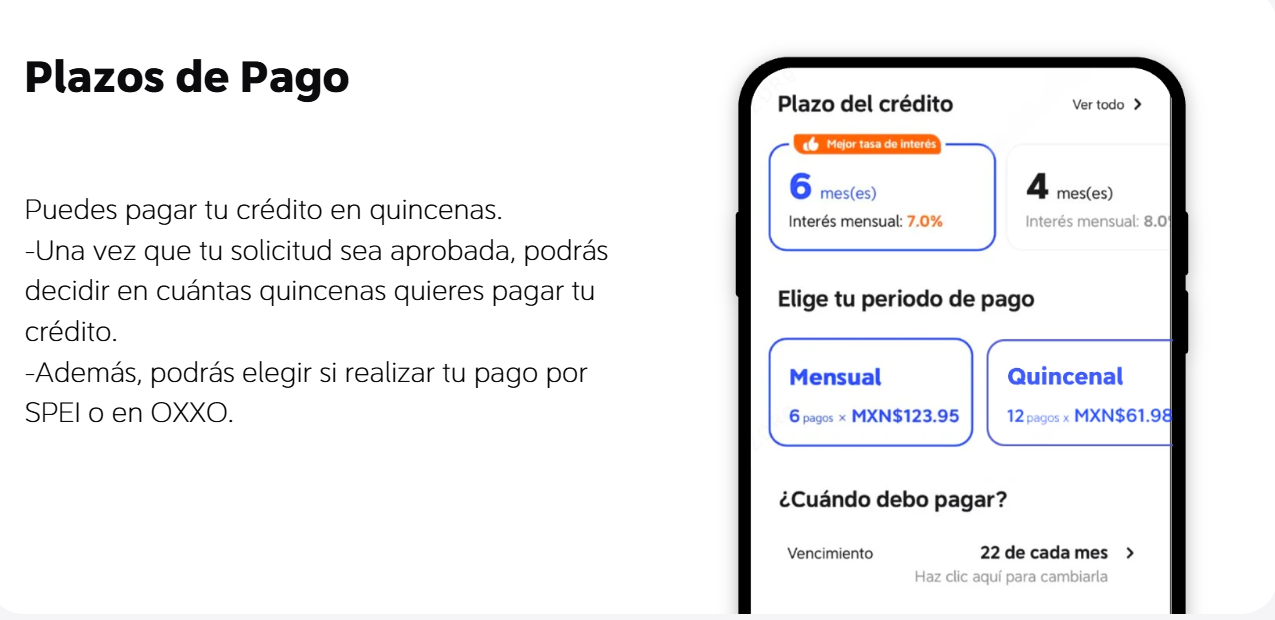
DiDi Finanzas focuses on two things most users care about: low friction and predictable costs. You get credit-card-style perks—no annual fee options and months without interest—wrapped in an app experience. The company leans on streamlined KYC and automated loan origination to move approvals fast. For people who need cash or an easier way to split purchases, the platform supports installment plans and clear APR info so you know what you’re signing up for. If you want quick small loans or card-like access, consider their prestamos en linea al instante offering as part of that mix.
How to apply, and the common mistakes to dodge
Start with the basics: have your ID, proof of income, and a clean phone camera for docs. Fill fields carefully—typos slow things down more than you’d think. Don’t pick the longest repayment just because monthly payments look smaller; you end up paying more in APR over time. Watch the fine print on promotional zero-interest months: missing one payment can cancel the promo and trigger backdated interest. Don’t overpromise — take the lower monthly payment that you can actually cover. That keeps your credit card utilization healthy and avoids surprise fees.
Alternatives worth comparing
DiDi Finanzas isn’t the only player. Traditional banks still offer wider branch networks and sometimes lower rates to long-term customers. Other fintechs may give instant credit but hide fees in late charges or high APRs. A quick checklist helps: compare total cost, the clarity of repayment schedules, and whether digital statements and customer service live in the app. For merchants and frequent travelers, rewards and acceptance matter too—so compare those extras before you commit.
Real-world context that matters
The shift to app-first finance isn’t theory — it showed up in daily life when commuting patterns changed after 2020. Cities across Mexico and Latin America saw faster adoption of mobile payments and lending apps. That behavioral change made people more comfortable getting credit on their phones and managing bills digitally. This matters because technology that mirrors how people already pay for rides and groceries reduces friction and builds trust faster than a traditional branch ever could.
Three metrics to judge if a service is right for you
1) Total Cost of Credit: Look past promos and add up fees plus APR over the term. That gives the real price, not just the flashy zero-interest months. 2) Time to Access Funds: Measure how long underwriting and disbursement take. If you need money fast, a two-week approval isn’t an option. 3) Transparency and Support: Check if the app shows payment schedules, penalty rules, and gives live help. Clear rules prevent nasty surprises.
Final take
Pick tools that actually make your day easier and don’t hide costs—those three checks will tell you most of what you need. For folks who want a quick, app-based route to no-annual-fee cards and interest-free installments, DiDi Finanzas fits naturally into that workflow. Simple. Smart. Fast. —
